Minimum Participation Rate Requirement
Minimum Participation Rate Requirement: Rules, Calculations & ICHRA Exemption
For small business owners and HR managers, the Minimum Participation Rate Requirement is one of the most stressful obstacles encountered during annual benefits renewals. A failure to collect enough employee enrollments can void an entire group health insurance contract.
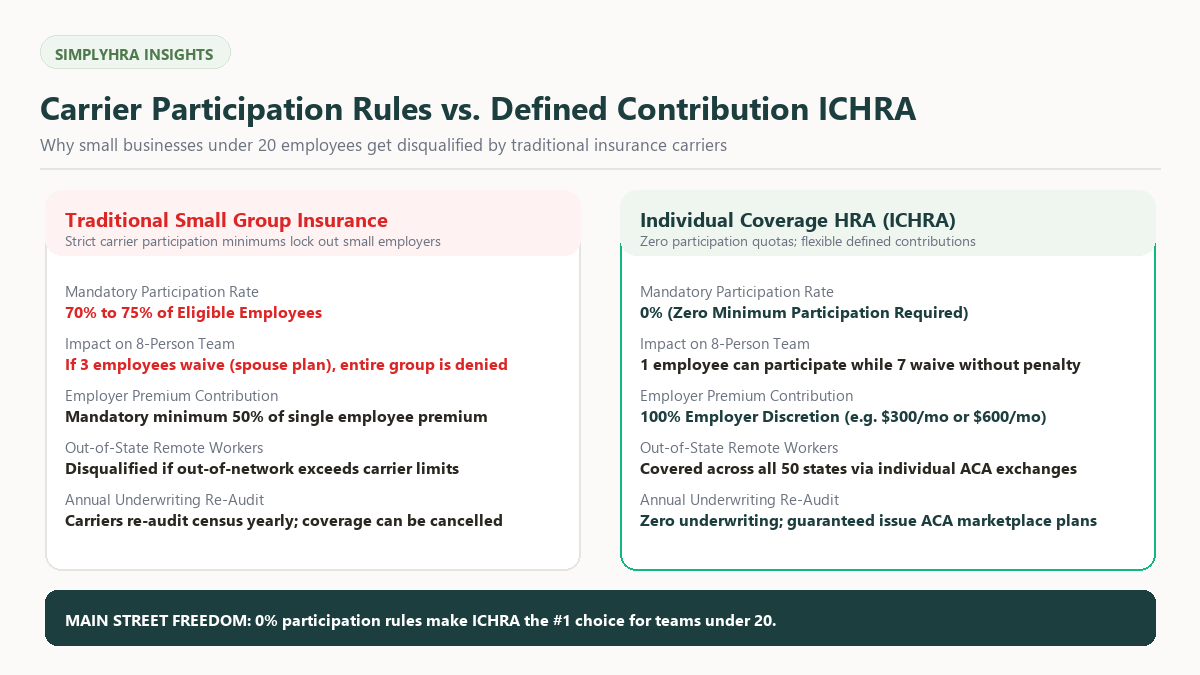
The 70% to 75% Small Group Participation Barrier
How Carriers Calculate Participation Rates
To determine if a business satisfies the participation threshold, insurance carriers apply a standard statutory formula:
Where Valid Waivers include employees who decline group coverage because they have verified alternative health insurance through:
- A spouse’s employer-sponsored group health plan
- Medicare (Part A and Part B)
- Medicaid or state children’s health programs (CHIP)
- Military TRICARE or VA healthcare benefits
The Small Business Participation Dilemma
Consider a 15-person company where 5 employees decline coverage because they are covered under a spouse’s plan (valid waivers). This leaves 10 eligible employees. If carrier rules require a 75% participation rate, at least 8 out of 10 remaining employees must enroll. If 3 younger employees opt out because their monthly payroll deduction is too expensive, the company achieves only 70% participation—and the carrier cancels the entire company’s health plan.
The Annual Special Open Enrollment Exemption
Under the Affordable Care Act (45 CFR § 147.104), carriers cannot enforce minimum participation or employer contribution rules if an employer applies for group coverage during the annual Special Open Enrollment Window (November 15 to December 15) for coverage effective January 1st. However, carriers can cancel or re-evaluate participation at the next off-cycle renewal.
Why ICHRA Completely Eliminates Participation Requirements
Under federal regulations governing Individual Coverage HRAs (26 CFR § 54.9802-4), no minimum participation requirement exists. Whether 2 workers or 50 workers take advantage of the company’s tax-free healthcare reimbursement allowance, the ICHRA remains active, legally compliant, and protected from cancellation.
Tired of Chasing Waivers to Meet Carrier Participation Rules?
Switch to SimplyHRA Defined Contribution. 0% minimum participation requirements, complete budget control, and full tax advantages under federal law.
See How ICHRA Solves Participation Friction →Related glossaries
Defined Contribution Healthcare
Minimum Participation Rate Requirement