ICHRA Guide for Businesses Offering Insurance First Time
ICHRA Guide for Businesses Offering Benefits for the First Time
TL;DR
Offering health benefits for the first time can be intimidating, especially when looking at the ever-increasing, unpredictable costs of traditional group plans. Individual Coverage Health Reimbursement Arrangement (ICHRA) gives growing businesses another option — one that doesn't require a broker, participation minimums, or several months to get off the ground.
CHOICE (Custom Health Option and Individual Care Expense) Arrangement is the current name for what was previously referred to as an ICHRA (Individual Coverage Health Reimbursement Arrangement). This page uses both terms.
Key Takeaways
- No size requirements: Group plans often require 70%+ employee sign-up just to qualify, whereas ICHRA can be offered whether you have just one employee or a large, multi-state workforce.
- No underwriting, no waiting: Group plans price against a claims history that a first-time benefits program doesn't have yet, which is exactly what ICHRA sidesteps.
- Allowance customization: ICHRA enables you to set different reimbursement allowances for different employee classes.
Group plans need a broker call, weeks of quoting, and often a minimum participation percentage before a carrier will even underwrite the group.
For a small, growing business, that's a lot of runway just to offer basic employee healthcare.
ICHRA skips most of that.
There are no broker cycles, participation requirements, or waiting times to worry about. You set reimbursement allowances, employees choose their own plan, and you can get your plan backend up and running in days.
Why Choose ICHRA as a First Benefit Offering?
Two things make traditional group health plans difficult for first-timers: the underwriting process and participation minimums.
ICHRA solves them both.
For starters, group carriers price a plan based on your group's claims history. That's data you don't have yet, which leads to slower quotes and less certainty about what you'll actually pay.
ICHRA skips underwriting entirely. Because you're not buying a policy, there's no group risk pool to assess.
It's all about setting an allowance and letting employees shop for a plan tailored to their specific needs.
Furthermore, ICHRA doesn't come with participation minimums, unlike group carriers that don't write policies unless a certain percentage of eligible employees sign up, which is often around 70%.
For a small team where a few people already have coverage through a spouse or a previous job, hitting that number can be genuinely difficult. But with ICHRA, every eligible employee can take the allowance, decline it, or ignore it, and the plan will still run.
Setting Up Your ICHRA Plan
Preparing an ICHRA plan is a lot simpler than most employers expect, even those who are offering benefits for the first time.
But before you get to work, there's a shortlist of requirements to take care of:
- Plan Document + Summary Plan Description (SPD): The formal paperwork establishing the ICHRA as an employee benefit plan and guiding employees on using their coverage.
- 90-day employee notice: Written notice explaining the allowance amount and its effect on marketplace subsidy eligibility, sent before the plan year begins.
- Consistent terms within each class: Whatever's offered to one employee should be offered to everyone else in the same class.
- Eligible medical expenses: Decide which medical expenses can be reimbursed under your ICHRA Plan.
Note: Read The Step-By-Step ICHRA Implementation Guide for the detailed setup process.
You can start creating employee classes, which is essentially about deciding who gets what.
A lot of first-timers can start with a single class covering the whole team at a set allowance amount, and that's completely fine. Nothing about ICHRA requires employers to deal with complexity on day one.
On SimplyHRA, this process runs through a self-service dashboard designed to feel less like HR software and more like setting up a social media profile.
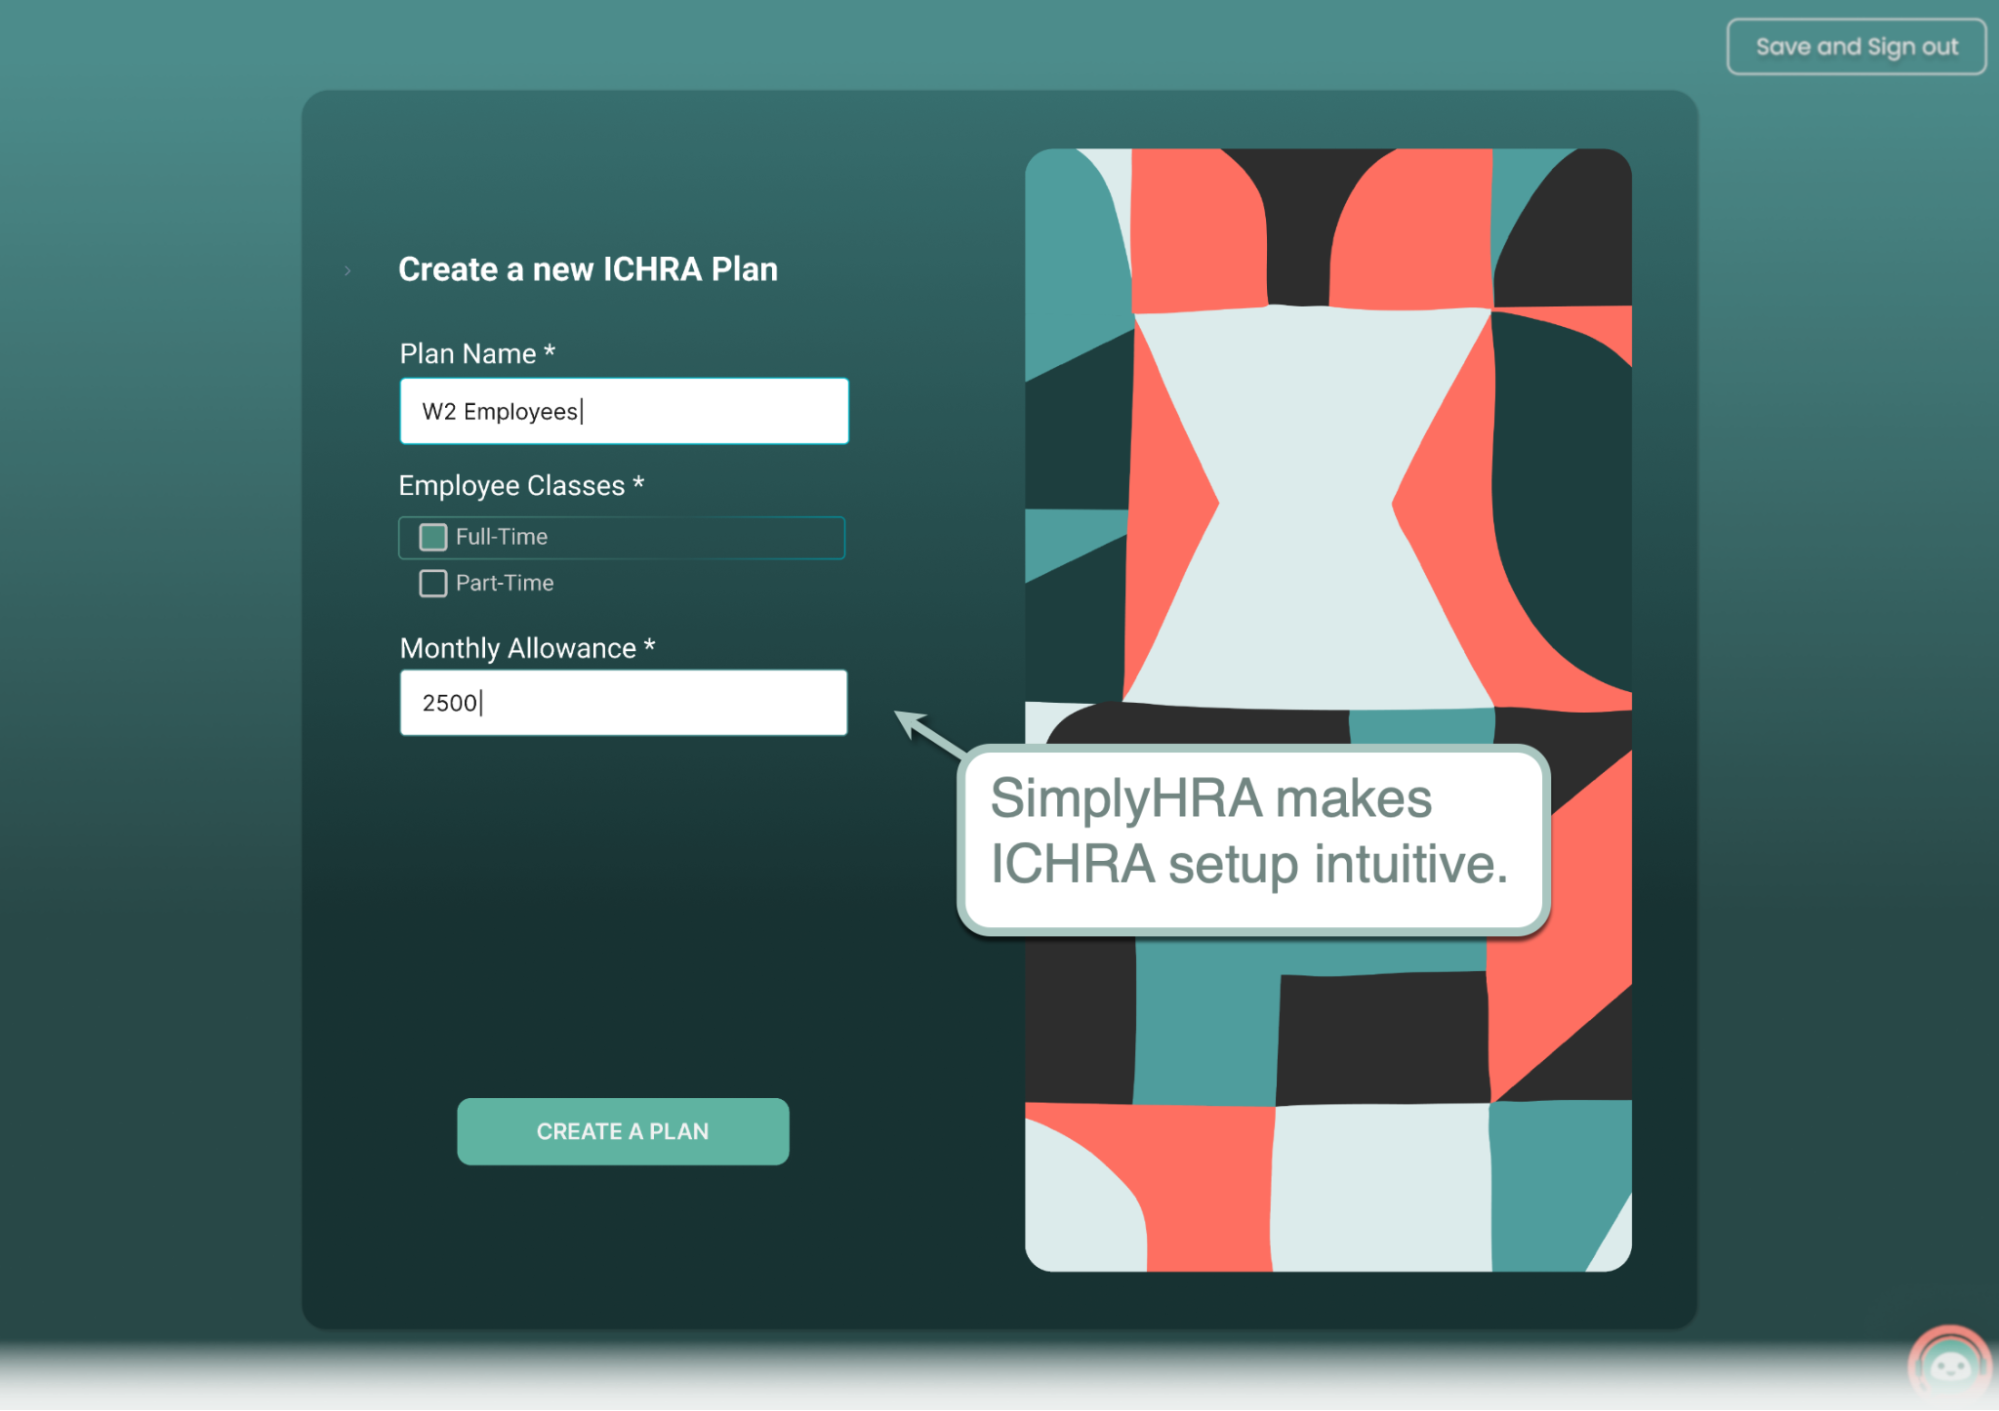
As the company grows and staffing gets less uniform, more classes can get added later. A typical setup involves two distinct ICHRA employee classes: full-time and part-time.
Apart from setting up your ICHRA plan, SimplyHRA is also equipped with tools for plan administration, employee onboarding, and reporting.
- Automatic payments: Just link your preferred business bank account for reimbursements, and payouts will be automated.
- Virtual cards: Employees can use their SimplyHRA virtual cards to pay for eligible medical expenses.
- AI assistant: Both you and your employees can use the built-in SimplyHRA AI assistant to receive instant answers and guidance.
- Data dashboards: Track your costs, budget, utilization, reimbursements, and more in real time.
What Employees Can Expect with Their First Employer Benefit?
For a lot of employees, this is new territory.
There's no "pick between our two group plans" moment. Instead, they're shopping the individual market themselves, sometimes for the first time in their careers.
That shift can feel like more responsibility, even when the coverage ends up just as good or better. Comparing plans, understanding deductibles, figuring out which doctors are in-network — none of that is intuitive if nobody's had to do it before.
A little support goes a long way.
On SimplyHRA, employees aren't left to figure everything out themselves. On top of the AI assistant providing 24/7 support, employees can also connect with our licensed benefits specialists via chat, email, phone, or a scheduled consultation.
Final Words
Offering benefits for the first time shouldn't require a broker relationship, a participation quota, or a few months of waiting to find out what you're even allowed to offer.
ICHRA cuts straight past that. Set an allowance, employees pick their own coverage, and the whole thing can be live in days — not because the paperwork disappears, but because a good platform streamlines the process.
See ICHRA in action by booking a SimplyHRA demo here.
Related blogs
Navigating ICHRA Compliance in 2026: Guide + Checklist
HMO vs PPO vs EPO for Employers